
Payment for dilapidations
Virtually all leases have clauses which stipulate that when the lease comes to an end, the tenant must leave the premises in the same condition as they were in when they entered them, and the negotiations over the termination of a lease will often involve a payment by the outgoing tenant to take account of the dilapidations.
In principle, the payment from the tenant to the landlord is to put the landlord back in the position it was in at the commencement of the lease: restoring the asset (the leased premises) to its former condition.
But how should such a payment be accounted for? Should it be treated as income in the hands of the landlord, and thus subject to taxation under the rules of income tax or corporation tax applying to income, or as a capital receipt and thus subject to the rules which apply to capital gains?
The case of Thornton v Revenue and Customs [2017] addressed this issue. It involved a landlord who let flats to a housing association. At the end of the lease, the housing association agreed to pay the landlord a dilapidations charge of £250,000. The landlord treated the receipt as a receipt of capital. HM Revenue and Customs took a different view, holding that it was a receipt of income.
The question turned on what gave rise to the legal right to receive the payment, which, as a matter of fact, was the agreement reached following negotiations between the landlord and the housing association. The building had become unfit for human habitation and required renovation before it could be let again.
The payment was made because the landlord had suffered a permanent diminution in the capital value of his asset and its purpose was to restore that value. It was, therefore, a capital receipt, not an income receipt. Had it been merely to provide income for the landlord during the period the flats could not be let, it would have been an income receipt.
In similar circumstances, the tax treatment of any such payment will depend on the facts of the individual case, and the wording of the agreement under which the payment is made will be a critical piece of evidence.
[edit] Related articles on Designing Buildings Wiki
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Government launches a one stop shop for flood preparedness.
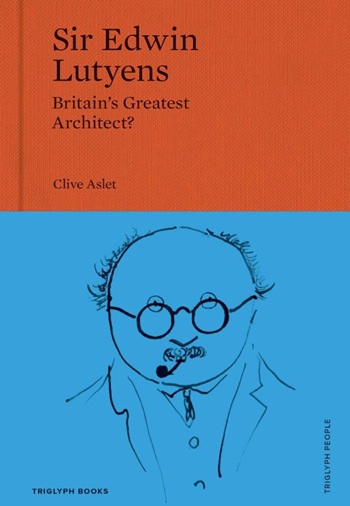
Sir Edwin Lutyens: Britain's greatest architect? Book review.
CIOB publishes free template to help assess and manage risks.
ECA's reflections on Party Conference season
Burnham wants to be confident of winning before asking for a fresh mandate.
New Chief Construction and Scientific Adviser
Sergio Cavalaro, Professor of Infrastructure Systems at Loughborough University.
Building safety levy for England
CIAT publish estimator tool for members.
Water sector faces a growing crisis that could slow the delivery of vital infrastructure.
Undervaluing our industrial past
Heritage value changes as taste for building styles changes.
Changing expectations around competence and compliance
New information sheet from CIAT.
Grenfell investigation files passed to CPS
Angela Rayner apologises on behalf of the British state.
Electrical contractors need to understand the practical implications.
The real barrier to getting more value from digital technology.
Comments