
Tax relief
Contents |
[edit] Introduction
Tax relief describes a situation in which an individual or company's liability to tax is reduced as a result of an entitlement to claim allowances or offset certain permitted expenditures against income.
[edit] Individuals
Individuals are entitled to personal allowances which provide tax relief by reducing taxable income. They can also obtain tax relief if they are able to utilise other allowances which HM Revenue and Customs permit in certain circumstances.
[edit] Personal allowances
These are set by HM Government and usually change each financial year to take account of changes in the cost of living. From time to time however these allowances may remain unchanged for a longer period of time. Depending upon the particular circumstances of each individual, the amount of the allowance is free from assessment to tax. The level of personal allowance depends upon age and also income.
For 2014/15 Personal Allowance:
- under 65 years of age £10,000
- 65 - 74 £10,500
- 75 and over £10,660
If an individual's income exceeds £100,000 the amount of the allowance reduces by £1 for every £2 income exceeds £100,000. Thus it can be seen that at an income level of £116,210 the allowance for an individual under 65 disappears completely.
Equally the higher allowances for older individuals are gradually reduced in much the same way as is the case for the basic personal allowance above £100,000. For 2014/15 the age related allowances begin to reduce at a rate of £1 for every £2 of earnings above £27,000 per annum.
Married Couples Allowance is available where one partner is at least 75 years of age in the financial year in question. Married Couples Allowance provides tax relief at 10%.
[edit] Pension contributions
Individuals may obtain tax relief by contributing to personal or occupational pensions schemes with a view to building up a fund to provide income in retirement. Contributions made in this way entitle the individual to tax relief at their marginal rate of tax. For a 40% taxpayer therefore, tax relief of £20,000 may be obtained against a contribution of £50,000. There are detailed rules and limits governing pension schemes and amounts that may be contributed, more details of which are available from HM Revenue and Customs.
[edit] Gift Aid/Deeds of covenant
Tax relief is available to support charitable giving. For a U.K. taxpayer the amount of the gift is deemed to be net of basic rate tax. In "grossing up" the value of the gift, relief is obtained at the taxpayers marginal rate. At the same time, the recipient of the gift can reclaim the basic rate of tax deducted at source.
[edit] Enterprise Investment Schemes (EIS)
Tax relief is also available to individuals who are prepared to invest in new businesses. The EIS pemits relief of 30% on the investment into shares in approved companies upto a maximum of £5,000,000. Thus maximum tax relief of £1,500,000 is available if the investors have sufficient taxable income against which the EIS relief can be set.
There is also a carry - back provision which permits the tax relief to be set against income tax liability arising in the tax year immediately prior to the year in which the share acquisition is effected. Shares must be held for a mnimum of three years otherwise the tax relief granted will be withdrawn.
[edit] Companies
Companies and non-incorporated businesses obtain tax relief by setting business running costs against income. They can also obtain relief by claiming capital allowances when they purchase assets for use in their businesses.
[edit] Related articles on Designing Buildings Wiki
- Budget.
- Business Asset Disposal Relief BADR.
- Capital allowances.
- Business case.
- Business plan
- Business rates.
- Cashflow.
- Cash flow forecast.
- Financial management tools.
- Funding options.
- Hourly rate.
- Housing Grants, Construction and Regeneration Act.
- PAYE.
- Payment for dilapidations.
- Research and development tax relief.
- Scheme for Construction Contracts.
- Staircase tax.
- Tax.
- VAT
- VAT - Option to tax (or to elect to waive exemption from VAT).
- VAT - Protected Buildings.
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Electrical contractors need to understand the practical implications.
The real barrier to getting more value from digital technology.
Your guide to The Construction Reset at UKCW Birmingham.
Accommodating the Victorian and Edwardian working woman. Book review.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
Shortlist for CIOB’s Art of Building photography competition.
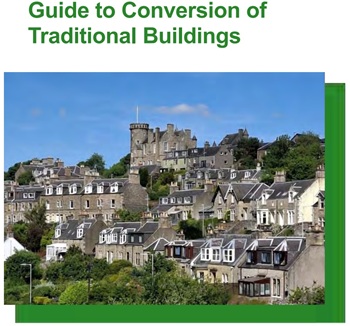
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
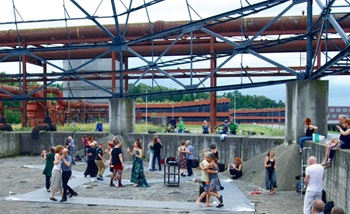
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.
Why diversity and inclusion matters for SMEs
CIOB’s D&I Charter shows how practical changes can support long-term growth.
Cut electricity bills to power growth
Coalition sends joint letter to the Chancellor.