
Capital
Contents |
[edit] Introduction
In classic economics, a country’s resources are called the ‘factors of production’ and are generally necessary to create goods and services (they do not form part of the final product).
The factors of production (FOP) are:
So, in this respect, strictly speaking, ‘capital’ amounts to those items that further the production process, such as tools, machinery, plant and equipment. (Some economists cite a fourth FOP: the entrepreneur, who takes the risks to organise the three factors and direct them to create new goods and services.)
However, a more contemporary definition might be the wealth (money or assets) that reveals the financial viability of an individual, organisation, or nation, and which is assumed to be available for development or investment. This may be further broken down into:
- Capital investment
- Capital employed and
- Working capital.
[edit] Capital investment
This is the amount of money (funds) that has been invested in a business (or project) to help achieve its objectives. The investment may come from the owner, shareholders, bondholders, equity investors, banks, venture capital, angel investors and lenders.
Capital investment may also refer to a firm’s acquisition of capital assets or fixed assets, such as plant and machinery.
The amount of invested capital is not usually listed as a separate line item on a firm’s balance sheet; it has to be inferred from other information in the firm’s accounting records.
[edit] Capital employed (or funds employed)
This is the total amount of capital being used in a firm to allow it to continue as a revenue-generating business. It is the total value of all the assets employed in the business and can be calculated by taking total assets and subtracting current liabilities (or fixed assets plus current assets minus current liabilities).
[edit] Working capital
This is the excess of the total current assets over the total liabilities of the firm (or current assets minus current liabilities). The formula measures a firm’s short-term liquid assets that remain after short-term liabilities have been paid off. An example would be as follows:
[edit] Current assets:
Cash £30,000
Inventories £10,000
Accounts receivable £30,000
Total £70,000
[edit] Current liabilities
Accounts payable £15,000
Short-term borrowings £10,000
Liabilities accrued £5,000
Total £30,000
So, the working capital is £70,000 - £30,000 = £40,000
[edit] Capital expenditure
Capital expenditure (sometimes abbreviated as Capex, CAPEX or CapEx) is one-off expenditure that results in the acquisition, construction or enhancement of significant fixed assets including land, buildings and equipment that will be of use or benefit for more than one financial year.
For more information see: Capical expenditure.
[edit] Capital Gains Tax
Capital Gains Tax (CGT) is levied on the profit that is made when something is sold, gifted, swapped or otherwise disposed of.
For more information see: Capital Gains Tax.
[edit] Related articles on Designing Buildings Wiki
- Budget.
- Capex.
- Capital allowances.
- Capital costs.
- Capital gains tax.
- Capital value.
- Cost plans.
- Depreciation.
- Human capital.
- Enhanced Capital Allowance scheme.
- Natural capital.
- Net Present Value.
- Produced capital.
- Social capital.
- Working capital
[edit] External references
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Changing expectations around competence and compliance
New information sheet from CIAT.
Grenfell investigation files passed to CPS
Angela Rayner apologises on behalf of the British state.
Electrical contractors need to understand the practical implications.
The real barrier to getting more value from digital technology.
Your guide to The Construction Reset at UKCW Birmingham.
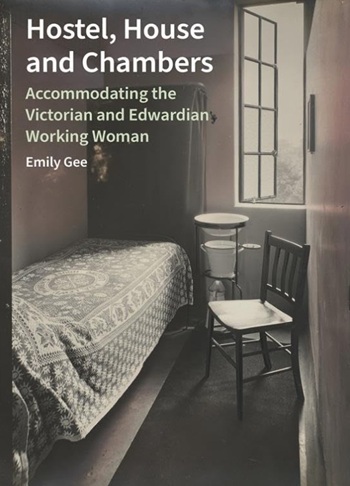
Accommodating the Victorian and Edwardian working woman. Book review.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
Shortlist for CIOB’s Art of Building photography competition.
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.