
Bridging loan for property
Contents |
[edit] Introduction
A bridging loan is a short-term funding solution which can be used to ‘bridge’ a gap between money being owed and credit becoming available. Typically, bridging loans are used in property transactions and can be essential in ensuring a property purchase can be achieved.
They often only take between seven and ten working days to organise, but can incur a large administration fee and high interest charges.
[edit] Details
Bridging loans are short-term finance options that enable a house buyer to complete a purchase before they sell their existing home through a high-rate interest loan. This type of finance option can also help home-movers if there is a gap between the sale and completion dates in a chain, for example somebody looking for a quick-sale after renovating a property or to help assist with purchasing at an auction.
There are two types of loans: closed and open. A closed bridge loan has a fixed repayment date. An open bridge loan does not have a fixed date, but is usually required to be paid off within a year. With closed bridge loans, the borrower will usually already have exchanged to sell a property and fixed the completion date.
[edit] Predominant target market
The typical recipients of bridging finance are landlords, small-scale property developers, and individual’s purchasing at an auction where finance is required quickly. Other recipients can include wealthy borrowers who require simple lending on residential properties.
It is possible to secure bridging loans against a variety of residential, semi-commercial, commercial or land and options can include:
- Properties to purchase: A new property, buy-to-let purchases, auction purchases.
- Properties to build and renovate: Housing developments, self-builds, barn conversions, refurbishment projects to sell for profit.
- Properties where funds are to be raised: Un-mortgageable properties, purchasing before selling, short-term cash flow solutions.
[edit] Sources of bridging finance
There are a wide variety of bridging lenders which range from small, one-man bands to larger professional organisations that are regulated by the Financial Conduct Authority.
NB Businesses can also use bridging loans secured against land and property to raise capital, to pay off tax liabilities, or to meet business obligations.
[edit] Related articles on Designing Buildings Wiki.
- Budget.
- Construction loan.
- Conveyancing.
- Cost plans.
- Credit check.
- Estate agent fees.
- Equity and loan capital.
- Funding options for building developments.
- Funding prospectus for new developments.
- How much does it cost to sell my home.
- Mezzanine finance.
- PF2.
- Private Finance Initiative.
- Project-based funding.
- Property development finance.
- Trade credit insurance.
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Accommodating the Victorian and Edwardian working woman. Book review.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
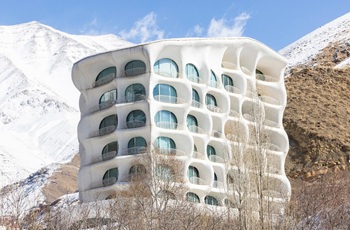
Shortlist for CIOB’s Art of Building photography competition.
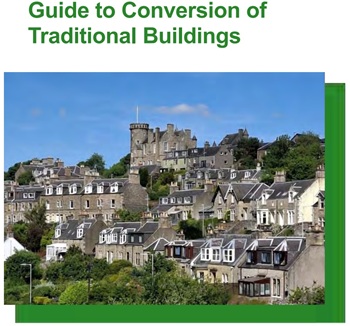
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.
Why diversity and inclusion matters for SMEs
CIOB’s D&I Charter shows how practical changes can support long-term growth.
Cut electricity bills to power growth
Coalition sends joint letter to the Chancellor.

Gasholders: a history in pictures. Book review.
Recognition, influence and growth
SocEnv identifies three strategic pillars in new strategy to 2045.
Discover the future of roofing, cladding and insulation.