
Industrial Buildings Allowance (IBA)

|
The Industrial Buildings Allowance (IBA) was introduced by the government in its 1945 Income Tax Act to boost post-war productivity in industry. The idea was that whatever the capital cost of constructing a manufacturing or processing building (or sometimes purchasing it 'second-hand’), the person holding 'the relevant interest' in the building would receive tax relief.
Aimed originally at productive industry, the scope of IBA was broadened to include allowances on infrastructure such as tunnels, bridges, roads used for highway concessions, qualifying hotels and commercial buildings in enterprise zones.
In effect, IBA was a writing down allowance (WDA) – allowing relevant business people to deduct a percentage of the value of an item from their profits each year, which in turn meant they paid less tax – typically for around 25 years, sometimes less. Thus, IBA constituted an incentive to build ‘industrial’ facilities.
However, the item had to count as ‘qualifying expenditure’ that had been incurred on a building.
IBA was made to the person holding relevant interest in relation to the qualifying expenditure. The relevant interest is defined by the construction expenditure incurred on the building; relevant interest therefore is the interest in the building to which the person who incurred the construction expenditure was entitled to when the expenditure was incurred. A building may have had several relevant interests, as construction expenditure could have been incurred at different times and by different people.
The following is an example of relevant interest given by UK tax collection service Her Majesty’s Revenue and Customs (HMRC, formerly ‘Inland Revenue’ for income tax collection):
"Warren builds a factory on land that he owns. The relevant interest for the factory is the freehold interest. If Warren leases the factory to Lowell and Lowell builds an extension, the relevant interest for the extension is Lowell’s leasehold interest. So, there are two relevant interests for the factory – Warren’s freehold interest for the factory and Lowell’s leasehold interest for the extension."
Buildings or constructions that qualified were:
- Buildings of a qualifying trade: e.g manufacturing/processing, storage, generating/transforming/converting, transmitting electrical energy
- Supplying water for public consumption
- Providing sewage undertakings
- Transport, inland navigation and dock undertakings (dock, wharf, pier etc)
- Tunnels
- Bridges (only if expenditure incurred after end 1956-57)
- Highways
- Undertakings for the supply of hydraulic power.
IBA allowances no longer exist. They were continuously in force from 1945 to 2008, after which they became the subject of a phased withdrawal until the financial year beginning April 1, 2011. Since then there have been no IBA writing down allowances.
[edit] Related articles on Designing Buildings
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
The real barrier to getting more value from digital technology.
Your guide to The Construction Reset at UKCW Birmingham.
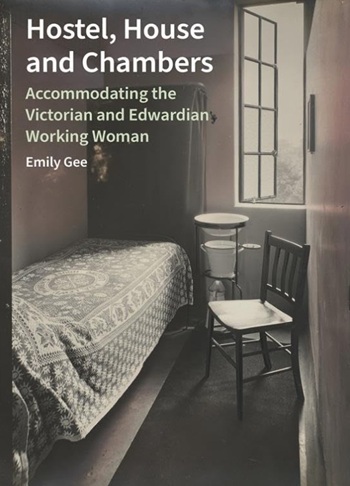
Accommodating the Victorian and Edwardian working woman. Book review.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
Shortlist for CIOB’s Art of Building photography competition.
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.
Why diversity and inclusion matters for SMEs
CIOB’s D&I Charter shows how practical changes can support long-term growth.
Cut electricity bills to power growth
Coalition sends joint letter to the Chancellor.

Gasholders: a history in pictures. Book review.