
Global smart water management
Aging pipe networks in several established cities are driving the demand for better water mains. For example, in London, approximately 40% of the pipes are more than 100 years old. Furthermore, according to the District of Columbia Water and Sewer Authority, the average age of it's city’s water pipes is 76 years.
There is a need to replace such water management systems with smarter, better systems. This, along with increasing government legislation is driving the global smart water management market, which is expected to demonstrate a marked compound annual growth rate (CAGR) of 17.7% from 2013-2019. The market was valued at US$4,813.3 million in 2012 and is projected to reach US$15,232.6 million by 2019.
The global smart water management market will also benefit from the growing need for mapping water resources and the need to reduce water loss and non-revenue water (NRW). In addition, the lack of water management systems in urban areas will provide good growth opportunities.
The global smart water management categorised by meter-read technology into fixed technology and cellular technology. On the basis of components, it can be categorised into; hardware (AMI, AMR, and others), solutions, and services.
The high cost associated with AMI installation will suppress the market, along with the apprehension of water utilities about the adoption of cloud services.
In spite of the high cost of AMI, the hardware segment in the global smart water management (SWM) market will continue to dominate the industry throughout the forecast period. In 2012, the hardware segment held the largest share, of the market, at 40.1%.
Geographically, the global smart water management market is divided into North America, Asia Pacific, the Rest of the World (RoW), and Europe. At present, North America dominates the market due to the high investment in smart water management technologies to curb water loss and optimise the NRW. In 2012, North America generated 47.5% of total revenue in the global smart water management market
Asia Pacific is predicted to demonstrate the highest CAGR of 23.7% during the forecast period. Factors such as higher rainfall variability, ageing facilities, the need for palatable and safe water, and the presence of countries rich in water resources will drive this regional market.
The global smart water management market is fragmented in nature with the presence of local players across the regions. 67.1% of the global smart water management market is held by regional and local companies. Notable players in the global smart water management market include ABB, Arad Metering Technologies, Schneider Electric, Sensus USA, General Electric Company, I20 Water, and TaKaDu.
[edit] Related articles on Designing Buildings Wiki
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Changing expectations around competence and compliance
New information sheet from CIAT.
Grenfell investigation files passed to CPS
Angela Rayner apologises on behalf of the British state.
Electrical contractors need to understand the practical implications.
The real barrier to getting more value from digital technology.
Your guide to The Construction Reset at UKCW Birmingham.
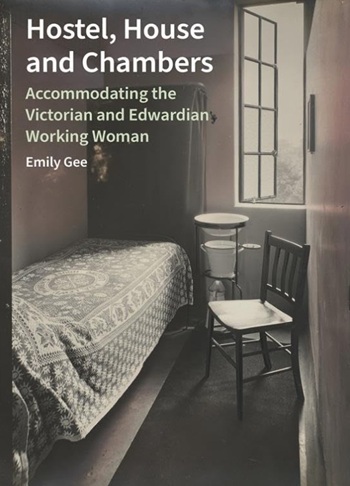
Accommodating the Victorian and Edwardian working woman. Book review.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
Shortlist for CIOB’s Art of Building photography competition.
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.