
Chattel
According to HMRC, a chattel is ‘…an asset, which is tangible and moveable’ (such as furniture). This is as opposed to a fixture, which is ‘…an asset that is installed or otherwise fixed in or to a building or land so as to become part of that building or land...’ (such as a boiler). For example, a bath may be a fixture, but a fridge a chattel.
HMRC suggest that ‘… a chattel may become a fixture if it is fixed to a building or land. For example, before it is installed in a building as part of a central heating system, a central heating radiator is a chattel. Once installed, it becomes a fixture.’
This can be particularly important in the sale of property or in leasehold agreements, where the distinction between fixtures and chattels can determine ownership.
There are two key tests for identifying whether something is a fixture or a chattel:
- The degree of physical affixation. This is not a conclusive test, but generally, the greater the degree of affixation (ie the damage that would be caused by removal) the more likely it is that an object is a fixture. The easier it is to remove, the more likely it is to be a chattel.
- More conclusively, if the object is intended to be permanent and effect a lasting improvement to the property, it is a fixture. However, if any attachment is intended to be temporary and no more than is necessary for the object to be used and enjoyed, then it is a chattel.
However, these tests are not always used as the basis for determining the right to remove an object. Leasehold agreements will generally distinguish between the landlord’s fixtures and tenants fixtures which they may remove at the end of the lease (as long as they make good any damage). Similarly, conveyancing reports for the sale of property may state that certain fixtures are not being sold as part of the land.
Disputes can arise in particular in relation to expensive items such as paintings that may to a greater or lesser extent be a part of the building in which they are housed. Where there is doubt, it may be advisable to seek legal advice, and ensure that the position is set out in writing before signing any agreement.
In addition, the distinction between fixtures and chattels is important when calculating stamp duty land tax. Fixtures form part of the taxable value of the purchase, whereas chattels do not. The inclusion of fixtures can move the saleable price for tax purposes to the next stamp duty threshold, resulting in a much larger tax liability for the purchaser than had been expected.
(Ref. HMRC, SDLTM04010 - Scope: How much is chargeable: Fixtures and fittings.)
HMRC suggest that:
The following items are, however, confirmed as being assets that will normally be regarded as chattels
- carpets (fitted or otherwise)
- curtains and blinds
- free standing furniture
- kitchen white goods
- electric and gas fires (provided that they can be removed by disconnection from the power supply without causing damage to the property)
- light shades and fittings (unless recessed).
On the other hand, the following items will not normally be regarded as chattels
- fitted kitchen units, cupboards and sinks
- agas and wall mounted ovens
- fitted bathroom sanitary ware
- central heating systems
- intruder alarm systems.
Externally, any plants, shrubs or trees growing in the soil which forms part of the land, are not to be regarded as chattels.
A deduction would, however, be appropriate for amounts properly apportioned to any plants growing in pots or containers.
[edit] Related articles on Designing Buildings Wiki
- Cupboards.
- Equipment.
- Fitting.
- Fixture.
- Furniture, fixtures and equipment.
- Premises.
- Room data sheet.
- Specification.
- Vacant possession.
[edit] External references
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
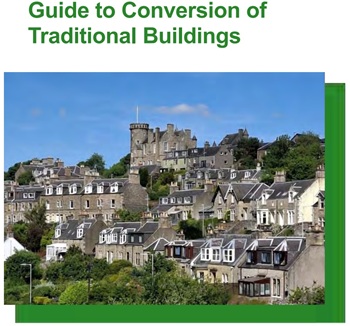
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.
Why diversity and inclusion matters for SMEs
CIOB’s D&I Charter shows how practical changes can support long-term growth.
Cut electricity bills to power growth
Coalition sends joint letter to the Chancellor.

Gasholders: a history in pictures. Book review.
Recognition, influence and growth
SocEnv identifies three strategic pillars in new strategy to 2045.
Discover the future of roofing, cladding and insulation.
New guidance for professional practice, cultural change and regulation in social housing.
The heritage of nuclear and conventional power stations.
New measures to stop people being ripped off
Government to protect families from cowboy builders and aggressive bailiffs.
New Futurebuild showcase brings an innovation-first approach.