
Floating charge
A floating charge is a type of security interest granted by a company over its assets. Unlike a fixed charge, which is tied to specific assets, a floating charge covers a class of assets that may change over time.
A floating charge applies to a general class of assets, such as stock, receivables, or inventory, which can change in the ordinary course of business. This flexibility allows the company to use and dispose of the assets without needing the lender's consent. Lenders, such as banks or financial institutions, use floating charges to secure loans. This provides them with a security interest over assets that are crucial to the company's operations but are not easily covered by fixed charges.
The floating charge applies to the specified class of assets until certain events occur, such as default on a loan, insolvency, or winding up of the company. It then becomes a fixed charge attached to the specific assets within the class that the company holds.
In the case of insolvence, floating charge holders rank after fixed charge holders and preferential creditors (such as employees and certain tax obligations) but before unsecured creditors.
In the construction industry, floating charges can be used to secure financing for various purposes, such as providing working capital while still holding assets that fluctuate in value and quantity, such as construction materials, equipment, and work-in-progress. A floating charge allows them to manage these assets dynamically while still providing security to lenders. For example, a construction company might secure a loan from a bank to finance a large project. The bank takes a floating charge over the company's inventory, accounts receivable, and other current assets. The company continues to use these assets in its operations. However, if the company defaults on the loan or becomes insolvent, the floating charge crystallises, converting into a fixed charge over the assets held at that time, giving the bank a priority claim over them.
Floating charges provide flexibility for the company to manage its assets without restricting the company's operational flexibility. However they give lower priority in insolvency compared to fixed charges, and settlement can become complex in terms of legal and financial management, especially at the point of crystallisation.
[edit] Related articles on Designing Buildings
- Bridging loan.
- Business process outsourcing (BPO).
- Buyer-funded development.
- Collateral.
- Construction loan.
- Construction project funding.
- Cost plans.
- Drawdown.
- Equity and loan capital.
- Funder.
- Funding options for building developments.
- Funding prospectus.
- Leaseback.
- Mezzanine finance.
- Private Finance Initiative.
- Project-based funding.
- Property development finance.
- Property valuation.
- Remortgage.
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Introduction to radon awareness
New technical information sheet published by CIOB.
Updated supplier guide can help electrical contractors engage with NHP.
CIAT confirm the winners of the 2026 architectural technology awards.
Government launches a one stop shop for flood preparedness.
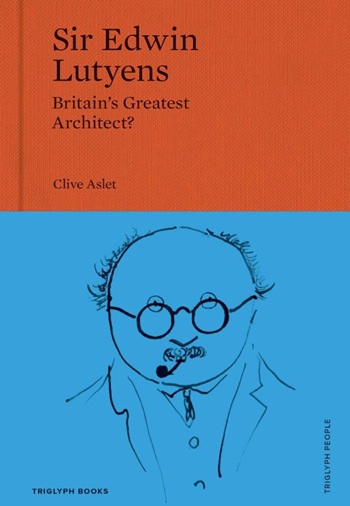
Sir Edwin Lutyens: Britain's greatest architect? Book review.
CIOB publishes free template to help assess and manage risks.
ECA's reflections on Party Conference season
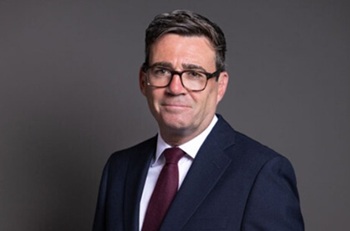
Burnham wants to be confident of winning before asking for a fresh mandate.
New Chief Construction and Scientific Adviser
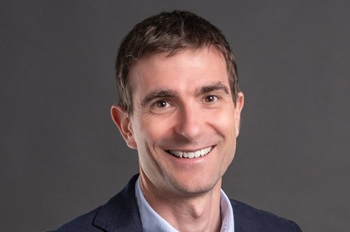
Sergio Cavalaro, Professor of Infrastructure Systems at Loughborough University.
Building safety levy for England
CIAT publish estimator tool for members.
Water sector faces a growing crisis that could slow the delivery of vital infrastructure.
Undervaluing our industrial past
Heritage value changes as taste for building styles changes.
Changing expectations around competence and compliance
New information sheet from CIAT.