
VAT refunds on self-build homes
Self-build homes and the conversion of non-residential buildings into dwellings may qualify to reclaim the VAT paid on eligible building materials and services. The building must not be intended to be used for business purposes.
The refund applies whether the home owner carries out the building work themselves, or whether they use builders to do some, or all of the work for them. Refunds are also permitted where the home owner adds to or finishes a partly completed new building, but not for extra work carried out on a completed building.
Claims to HMRC can only be made once the construction is finished. Completion can be demonstrated by:
- A certificate or letter of completion from the local authority for building regulations purposes.
- A habitation certificate or letter from the local authority.
- A valuation rating or council tax assessment.
- A certificate from a bank or building society.
Claims must be made within three months of completion and refunds will normally be made within 30 banking days of receiving the claim.
Making a claim requires that VAT invoices have been obtained and that they are correct. VAT invoices must show:
- The supplier's VAT registration number.
- The quantity and description of the goods and/or services.
- The purchaser’s name and address if the value is more than £100.
- The price of each item.
It is much easier to collect, collate and process the appropriate paperwork as project progresses than it is to try to do so after the building is complete.
Claims can be made for:
- Building materials or goods incorporated into the building or conversion itself, or into the site (that is materials or goods that cannot be removed without using tools and damaging the building or the goods themselves). Exceptions include; fitted furniture, some electrical and gas appliances, and carpets or garden ornaments.
- If you are converting a non-residential building into a home, you can reclaim the VAT charged by your builder. For conversions, a builder can sometimes charge you a reduced rate instead of the standard rate of VAT.
Builder's services for new buildings should be zero-rated for VAT.
VAT paid on any professional or supervisory services cannot be reclaimed (although in kit houses this may be wrapped-up in the price of the kit), neither can VAT paid on services such as the hire of plant, tools and equipment.
[edit] Related articles on Designing Buildings Wiki
- Business rates.
- Kit house.
- PAYE.
- Self build.
- Self-build home project plan.
- Self-build homes negotiating discounts.
- Self build initiative.
- Stamp duty.
- VAT
- VAT - Option to tax (or to elect to waive exemption from VAT).
- VAT - Protected Buildings.
[edit] External references
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Your guide to The Construction Reset at UKCW Birmingham.
Accommodating the Victorian and Edwardian working woman. Book review.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
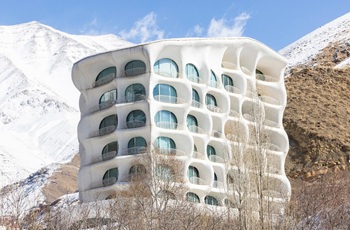
Shortlist for CIOB’s Art of Building photography competition.
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.
Why diversity and inclusion matters for SMEs
CIOB’s D&I Charter shows how practical changes can support long-term growth.
Cut electricity bills to power growth
Coalition sends joint letter to the Chancellor.

Gasholders: a history in pictures. Book review.
Recognition, influence and growth
SocEnv identifies three strategic pillars in new strategy to 2045.