
Capital allowances and super deductions
Contents |
[edit] Introduction
As part of the Government’s post COVID-19 recovery planning, two capital allowance relief initiatives became effective as of 1 April 2021. These relief measures, which run until 31 March 2023, are meant to encourage spending on new plant and equipment for use in a business in any event, as well as to assist companies that need to undertake such expenditures as part of their own strategy to recover from the effects of the pandemic.
[edit] Details
Office furniture, computer equipment and items such as photocopiers, scanners and telephone equipment, security systems and even carpeting all fall under the heading of plant and equipment.
The two relief measures are:
- A 130% super-deduction capital allowance for qualifying plant and machinery investment. The 130% allowance is for assets that would normally qualify in the main pool for capital allowances with a writing down allowance (WDA) of 18%.
- A 50% first-year allowance (FYA) for special rate assets. The 50% FYA is for assets that normally qualify in the special rate pool with a WDA of 6%. These are integral features such as air-conditioning, lifts and water heating systems.
[edit] Reasoning behind the initiatives
Reorganising space to deal with the consequences of the pandemic may well mean a substantial outlay on capital items, and these provisions are designed to alleviate the financial costs associated therewith.
The 130% allowance means that for every £100,000 of qualifying expenditure, the deduction for copropration tax purposes is 30% higher than what is actually incurred. At a corporation tax rate of 19% (current as of April 2021) this means an additional 5.7% tax savings on every £100,000 actually spent.
Items which are considered to be general in nature (i.e not long-lasting capital assets) do not qualify for this treatment.
Unfortunately, cleaning items, hand sanitisers and PPE (disposable or reusable) typically fall under the general expenditure. Therefore, capital allowances would not usually be applicable to these items.
And finally, if the assets are disposed of before 1 April 2023, a balancing charge will be due. This will allow HMRC to recover the tax relief given.
[edit] Annual Investment Allowance (AIA) applicability
Please note that these provisions do not apply to individuals or partnerships. For sole traders or partnership, the Annual Investment Allowance (AIA) is more appropriate.
The AIA continues to be available alongside the new measures and remains at £1m until 31 December 2021 before dropping to just £200,000. The AIA covers leased and second-hand assets.
--Martinc 16:24, 04 May 2021 (BST)
[edit] Related articles on Designing Buildings Wiki
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Your guide to The Construction Reset at UKCW Birmingham.
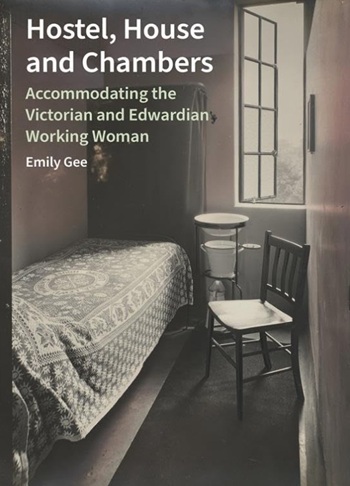
Accommodating the Victorian and Edwardian working woman. Book review.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
Shortlist for CIOB’s Art of Building photography competition.
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.
Why diversity and inclusion matters for SMEs
CIOB’s D&I Charter shows how practical changes can support long-term growth.
Cut electricity bills to power growth
Coalition sends joint letter to the Chancellor.

Gasholders: a history in pictures. Book review.
Recognition, influence and growth
SocEnv identifies three strategic pillars in new strategy to 2045.