
Research and development tax relief
Research and development tax relief is a specialist piece of tax relief made available by governments to provide incentives to businesses. It is designed to provide support to companies who invest in research and development (R&D), to help bring new products to market, to develop new processes, or to improve existing products or processes.
R&D tax relief should be considered at the start of a project as it can have a significant impact on costs and the budget and may even make an unfeasible project, feasible. Tax relief mechanisms may vary widely in different countries and for different periods of time, so should be checked based on location and year of application.
This article is aimed primarily at companies operating in the UK, there are similar schemes in many EU countries. In the 2023 spring budget the UK Government made a number of significant changes to the mechanisms relating to Research and Development tax relief, in particular with respect to small and medium enterprises (SME's)
There are two schemes available to UK companies, an SME Scheme, aimed at Small to Medium Sized Companies, (SME R&D relief) and a large company scheme for companies that do not meet the criteria of the SME Scheme referred to as Research and Development Expenditure Credit (RDEC).
To qualify for the SME Scheme the following criteria need to be met:
- Less than 500 staff
- A turnover of under 100 million euros or a balance sheet total under 86 million euros
Partner and linked enterprises, may also need to be included when assessing if the company is an SME, but the SME R&D relief allows companies to:
- Deduct an extra 130% of their qualifying costs from their yearly profit, as well as the normal 100% deduction, to make a total 230% deduction
- Claim a tax credit if the company is loss making, worth up to 14.5% of the surrenderable loss
To get R&D relief a project needs to explain how it;
- looked for an advance in science and technology
- had to overcome uncertainty
- tried to overcome this uncertainty
- could not be easily worked out by a professional in the field
The project may research or develop a new process, product or service or improve on an existing one.
Any company that does meet the criteria of the SME Scheme is eligible to claim under the Large Company Scheme.
The Research and Development Expenditure Credit is a tax credit, it was 11% of qualifying R&D expenditure up to 31 December 2017 and was increased to:
- 12% from 1 January 2018 to 31 March 2020
- 13% from 1 April 2020
SMEs and large companies who have been subcontracted to do R&D work by a large company can also claim under the schemes.
In September 2020, HM Revenue & Customs reported that £175m was paid to UK construction firms in research and development tax credits in the previous year,a significant increase on the £90m paid the year before.
[edit] Related articles on Designing Buildings
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Your guide to The Construction Reset at UKCW Birmingham.
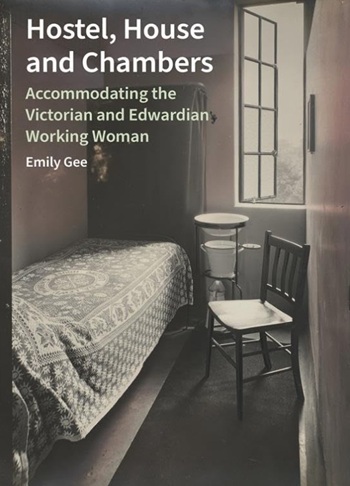
Accommodating the Victorian and Edwardian working woman. Book review.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
Shortlist for CIOB’s Art of Building photography competition.
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.
Why diversity and inclusion matters for SMEs
CIOB’s D&I Charter shows how practical changes can support long-term growth.
Cut electricity bills to power growth
Coalition sends joint letter to the Chancellor.

Gasholders: a history in pictures. Book review.
Recognition, influence and growth
SocEnv identifies three strategic pillars in new strategy to 2045.