




Relevant cost
Relevant cost, also known as differential cost, is an accounting term that is used to refer to costs that pertain to a particular decision. This means that those costs could be avoided depending on whether the decision is taken. Relevant costs will differ between the alternative options being considered.
By identifying the relevant costs that relate to a particular decision, cost information that is common to all options, and so not relevant to the decision can be removed; these are referred to as irrelevant costs. Time and effort can be saved by distinguishing between relevant and irrelevant costs when analysing options.
Relevant costs are typically considered in two categories:
- Future cost: The cost that will be incurred in the future as a result of the decision (If this future cost does not change based on the decision then it is an irrelevant cost).
- Opportunity cost: The amount that will be lost in terms of missed opportunities as a result of the decision.
[edit] Related articles on Designing Buildings Wiki
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.

CIAT reflects on the party conferences.

CIOB announce the winners of the Art of Building photography competition.

National Scheme of Delegation introduced.

The cost of employing people remains a concern.
Code of Practice for Electrical Energy Storage Systems.

ECA calls on members to comment on draft 4th edition.

Bringing together expertise and creating cultural benefits.

CIOB celebrates positive Ofsted report.

The Building Safety Regulator announces a call for evidence.

Government approach could undermine delivery and regeneration.
World's first mass timber data centre.
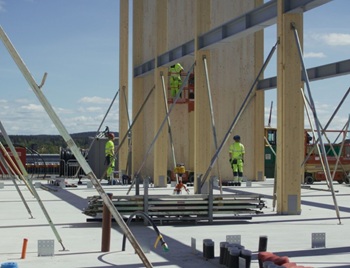
The overlooked environmental aspect of data centre development.
Introduction to radon awareness
New technical information sheet published by CIOB.
Updated supplier guide can help electrical contractors engage with NHP.